Vendor Financing Examples for Commercial Fleets
Vendor financing examples show how fleets can buy equipment, preserve working capital, and coordinate dealers, delivery, and lender requirements clearly.

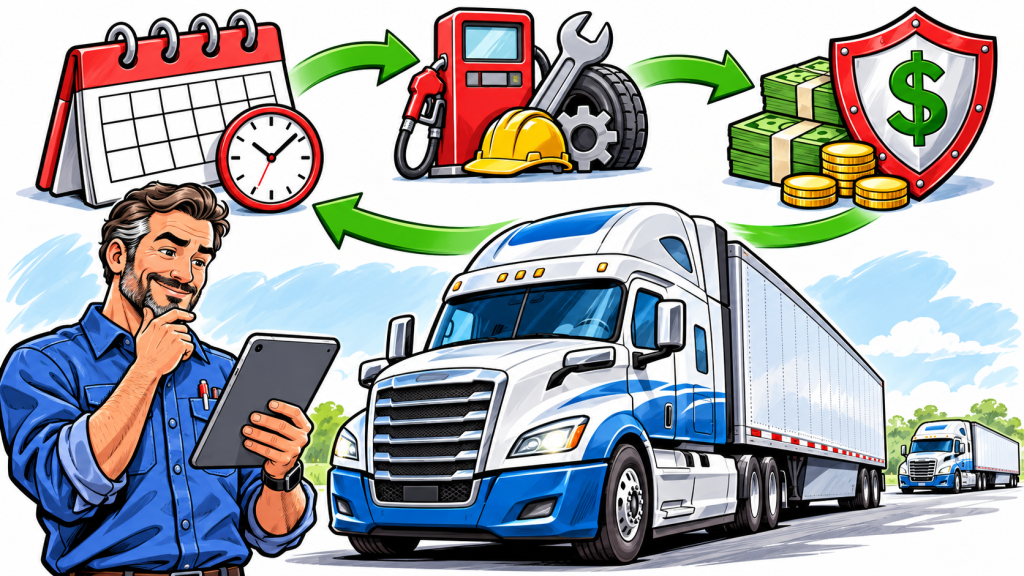
A truck can be profitable on paper and still put pressure on the business if its payment, fuel, payroll, insurance, repairs, and customer payment cycle are out of step. This guide to fleet cash flow is for established operators making practical decisions about when to replace, add, or finance revenue-producing equipment without draining the capital needed to run the operation.
Fleet cash flow is not simply the money left after a monthly truck payment. It is the timing of cash entering and leaving the business. A growing carrier, towing company, contractor, medical transport provider, or vocational fleet may have solid booked work and healthy assets but still face a cash squeeze when several obligations hit before receivables clear.
The most useful starting point is to map how long cash is tied up between operating the equipment and collecting payment for the work it performs. In trucking, that may mean fuel, driver pay, tolls, maintenance, and insurance are paid weekly or monthly while certain customers pay invoices in 30, 45, or 60 days. In construction, equipment may be working on a project before progress billing is approved and paid.
A fleet payment has to fit within that timing gap, not just within an annual profit forecast. A business can afford an asset over five years but still struggle if the first several payments coincide with a seasonal slowdown, a large insurance deposit, or delayed customer receivables.
Review at least 90 days of actual cash activity before committing to a purchase. Compare customer payment timing, payroll dates, fuel spend, repair costs, insurance, taxes, debt service, and planned capital expenses. Then look ahead at the next six to twelve months. This makes it easier to identify months when cash is naturally tighter and structure the acquisition accordingly.
The down payment is only one part of the cash required to put a truck, trailer, excavator, rollback, or box truck into service. Operators should also account for taxes and registration where applicable, insurance adjustments, delivery or transport, inspections, permitting, upfitting, initial maintenance, telematics, decals, and driver onboarding.
For example, a company buying a used dump truck may have enough cash for a 15% down payment but still need funds to install a body, complete repairs identified during inspection, and cover higher insurance costs. Using every available dollar for the purchase can leave no margin for those expenses.
That does not mean every business should put the least possible cash down. A larger down payment can improve the financing structure, reduce the payment, and help where an asset is older, higher mileage, specialized, or purchased from a private seller. The right choice depends on the company’s liquidity, credit strength, fleet history, asset, and expected revenue from the unit.
A practical rule is to preserve enough operating capital to handle normal obligations and a credible disruption, such as a major repair, a customer paying late, or a temporary decline in utilization. The exact reserve differs by industry and fleet size, but the principle is consistent: equipment should support operations, not force the business to run without a cushion.
A payment should reflect how the equipment earns revenue. A day-cab tractor running contracted regional freight has a different cash profile than a wrecker serving municipal rotation work, a seasonal landscaping fleet, or an excavator deployed across long-term projects.
Term length is often the first lever businesses consider. A longer term may lower the monthly payment and preserve near-term working capital. The tradeoff is that total financing cost may be higher over time, and the business may carry debt longer than it wants to keep the asset. A shorter term can reduce total cost and build equity faster, but it places more pressure on monthly cash flow.
Asset age and expected useful life matter. A newer semi-truck, trailer, or well-specified vocational unit may support a longer structure than an older truck with high mileage or a specialized asset with a narrower resale market. Lenders also evaluate these factors, along with the asset’s condition, seller type, and intended commercial use.
Payment timing can matter as much as payment size. Monthly payments are common, but some businesses have revenue patterns that justify discussing other structures when available. Seasonal work, large project cycles, and contractual billing schedules should be addressed before documents are prepared, not after funding.
Keeping an older unit paid off can look like the cheapest option until downtime becomes frequent and unpredictable. A truck that misses several days of dispatch may create costs beyond the repair invoice: rental expense, overtime, subcontracted work, missed loads, customer frustration, and idle labor.
Replacement is often a cash-flow decision before it is a cosmetic one. Review each unit’s repair history, downtime, utilization, fuel performance, safety-related issues, and availability of replacement parts. If a unit is becoming unreliable, the relevant comparison is not zero payment versus a new payment. It is the total operating cost and revenue risk of retaining it versus the cost of replacing it.
A replacement does not automatically make sense just because a newer asset has better specifications. If the current unit is reliable, lightly utilized, and appropriate for the work, retaining it may preserve capital. The case for replacement becomes stronger when uptime is limiting revenue, maintenance is becoming erratic, or the business cannot confidently commit the unit to customer work.
Many acquisition decisions are built around a best-case revenue estimate. A stronger approach uses a conservative utilization assumption and asks whether the payment still works if the unit is not fully deployed immediately.
For a new tow truck, estimate the number of billable calls required to cover its full monthly ownership cost, including payment, insurance, maintenance reserve, fuel, labor, and administrative overhead. For a tractor or box truck, estimate required loaded miles or route revenue. For construction equipment, calculate the expected billable hours and include likely idle periods between projects.
Do not rely entirely on projected revenue from an asset that has not yet been assigned work. Existing contracts, repeat customers, dispatch history, backlog, and documented demand provide a better basis for planning than general optimism about market conditions.
A financed asset still needs a repair reserve. Even late-model equipment can require tires, brakes, wear items, service work, and unexpected repairs. Used equipment requires especially careful evaluation because its purchase price may be lower while near-term maintenance needs are higher.
Before submitting a finance request, gather maintenance records when available and understand the unit’s condition, mileage, hours, specifications, and any required upfit. An experienced finance partner can help identify the information lenders are likely to need, but the business should also evaluate the operating exposure for itself.
This is particularly relevant for used vocational trucks, older trailers, yellow iron, and units bought through private-party transactions. Those deals can be workable, but lender requirements, advance rates, inspections, and documentation may differ from a new purchase through an established dealer.
A well-prepared borrower usually has more options and fewer avoidable delays. For established businesses, common items may include recent business bank statements, financial statements or tax returns when requested, debt schedules, ownership information, equipment quotes, and details about the asset’s commercial use.
The strength of the request is not based on credit alone. Time in business, payment history, fleet experience, profitability, liquidity, existing debt, asset type, mileage or hours, and whether the seller is a dealer or private party can all affect available structures. A business with strong credit may still face a different review for a high-mileage truck or specialized unit than for a standard late-model trailer.
It helps to explain the business case clearly: whether the equipment replaces an aging unit, supports a signed contract, adds capacity to an established route, or reduces reliance on rentals and subcontractors. That context can help the financing request reflect the actual transaction rather than a generic application.
Commercial Fleet Financing works as a specialized equipment finance broker and financing partner, helping qualified businesses present equipment transactions to appropriate funding sources and coordinate the documentation and vendor process. Approval timing and terms depend on the borrower profile, asset, documentation, lender requirements, and deal structure.
Before accepting a purchase order or finance agreement, ask three direct questions. First, can the business make the payment during a slower-than-expected month without affecting payroll, insurance, or core operating obligations? Second, does the equipment have a credible path to producing enough revenue or avoiding enough downtime to justify its total monthly cost? Third, does the purchase leave sufficient cash for the work required to put the asset into service?
If the answer to any of those questions is unclear, the next step may be to revise the asset selection, down payment, term, or purchase timing. Good fleet cash flow planning is not about avoiding financing. It is about using financing deliberately, so the equipment can go to work while the business keeps the capital needed to operate with confidence.
Vendor financing examples show how fleets can buy equipment, preserve working capital, and coordinate dealers, delivery, and lender requirements clearly.

Use this used truck age requirements guide to assess lender limits, mileage, condition, seller rules, and financing options before buying any commercial truck.

Learn how to fund ambulance replacements with financing structures that protect cash flow, meet lender requirements, and put dependable units into service.

Learn how to coordinate dealer equipment funding, align documents and delivery, and keep qualified commercial equipment purchases moving forward on time.
See how lender underwriting evaluates your business, equipment, cash flow, and documents so you can structure a commercial equipment deal with less delay.